Last year almost nine million U.S. households had a net worth of at least $1 million, excluding primary residence. The heads of most of those millionaire households were under 60. Who says Boomers can't hang onto money?
Saving and investment was the primary source of this household wealth. Only 19% reported having shared ownership of a business or professional partnership.
Two out of every five millionaire households don't yet have an investment advisor. Gentlemen and ladies, start your sales presentations!
Thursday, March 30, 2006


The bad news: Most Boomers won't inherit more than chump change
Most Americans born between 1946 and 1964 have little hope of an inheritance, as The New York Times reported recently.
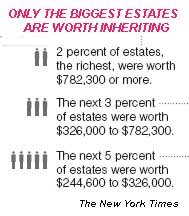
Hundreds of billions of dollars are passing through estates each year, but about 7% of estates account for half the total wealth.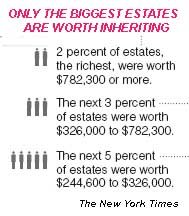
Hundreds of billions of dollars are passing through estates each year, but about 7% of estates account for half the total wealth.
Tuesday, March 21, 2006
Why Americans save less than nothing (Hint: it's homeland security)
Randy Cassingham's This is True newsletter called my attention to this amazing story, reported by the Providence Journal.
Running up debt has become such a dominant theme of national policy that individual Americans who don't follow suit are now suspected of treason.
All the poor guy did was try to pay down his credit card debt. That Un-American activity was sufficient to ID him as a potential terrorist. Presumably, Dubya, Dick and Rummy figured Walter Soehnge was recharging his available credit so he could buy a plane ticket and crash into the Washington Monument.
I sure can see why Walter was "madder than a panther with kerosene on his tail."
Looks like it's time for a career change, folks. Get out of wealth management and into debt counselling!
Running up debt has become such a dominant theme of national policy that individual Americans who don't follow suit are now suspected of treason.
All the poor guy did was try to pay down his credit card debt. That Un-American activity was sufficient to ID him as a potential terrorist. Presumably, Dubya, Dick and Rummy figured Walter Soehnge was recharging his available credit so he could buy a plane ticket and crash into the Washington Monument.
I sure can see why Walter was "madder than a panther with kerosene on his tail."
Looks like it's time for a career change, folks. Get out of wealth management and into debt counselling!
Monday, March 20, 2006
Why worry about inflation? Because it's creepy.
Consumer prices barely budged last month. For the twelve months ending in February, the CPI crept up a mere 3.6%.
Somehow, inflation in real life doesn't seem that tame. Wondering why, I consulted the list of price changes recorded by The Wall Street Journal in its year-end reviews. Here's a sampling of price changes from 2000 to 2005:
To be fair, a Big Mac isn't the only item that costs less than it did five years ago. Prices of laptops and TVs have come down, too. But the proliferation of technical gadgets has probably cancelled out any net advantage for many families. Ringtones, iPods, iTunes downloads and assorted other teenage necessities were luxuries or unobtainable five or ten years ago.
Even 3.6% inflation can get nasty in the long run. The other day on the radio, a financial planner was urging 40-year-olds with no savings to start investing enough to give them a $1-million retirement fund by age 65. That won't be easy, and it may not be adequate.
If inflation creeps at an average rate of only 3.6%, their million will have no more buying power than $415,000 or so has today.
Somehow, inflation in real life doesn't seem that tame. Wondering why, I consulted the list of price changes recorded by The Wall Street Journal in its year-end reviews. Here's a sampling of price changes from 2000 to 2005:
Big Mac DOWN 4%
Pair of jeans UP 4%For some of the above, obviously, inflation has done more than creep.
Midsize auto UP 9%
Funeral UP 16%
Movie ticket UP 22%
Unleaded gasoline UP 49%
Year in college (Penn State) UP 54%
Single-family home UP 55%
Day in hospital UP 87%
Clearing clogged sink (Roto Rooter) UP 138%
To be fair, a Big Mac isn't the only item that costs less than it did five years ago. Prices of laptops and TVs have come down, too. But the proliferation of technical gadgets has probably cancelled out any net advantage for many families. Ringtones, iPods, iTunes downloads and assorted other teenage necessities were luxuries or unobtainable five or ten years ago.
Even 3.6% inflation can get nasty in the long run. The other day on the radio, a financial planner was urging 40-year-olds with no savings to start investing enough to give them a $1-million retirement fund by age 65. That won't be easy, and it may not be adequate.
If inflation creeps at an average rate of only 3.6%, their million will have no more buying power than $415,000 or so has today.
Friday, March 17, 2006
The Dow hit five-year highs this week. Is it on its way to the stars?
To celebrate the Dow's resurgence, you and your clients might enjoy tackling the question Warren Buffet posed in his Berkshire-Hathaway shareholders letter:
Q. Between December 31, 1899 and December 31, 1999, the Dow
rose from 66 to 11,497. Guess what annual growth rate is required to produce this result.
A. The Dow increased from 65.73 to 11,497.12 in the 20th century, and that amounts to a gain of 5.3% compounded annually. (Investors would also have received dividends, of course.) To achieve an equal rate of gain in the 21st century, the Dow will have to rise by December 31, 2099 to – brace yourself – precisely 2,011,011.23. But I’m willing to settle for 2,000,000 . . . .
Q. Between December 31, 1899 and December 31, 1999, the Dow
rose from 66 to 11,497. Guess what annual growth rate is required to produce this result.
A. The Dow increased from 65.73 to 11,497.12 in the 20th century, and that amounts to a gain of 5.3% compounded annually. (Investors would also have received dividends, of course.) To achieve an equal rate of gain in the 21st century, the Dow will have to rise by December 31, 2099 to – brace yourself – precisely 2,011,011.23. But I’m willing to settle for 2,000,000 . . . .
Thursday, March 09, 2006
To hedge-fund investors, those red flags still look green
 Troubles at Atlanta Hedge Fund Snare Doctors, Football Players, The Wall Street Journal reports. Which proves that wealthy doctors and millionaire footballers are just as colorblind as investors in various other hedge funds, like Bayou, that now exist only in painful memory.
Fund manager Kirk S. Wright said he generated returns of 27% per annum, the Journal notes:
In hindsight, there were many red flags at International Management: unusually consistent high returns, vague descriptions of investment strategies, aggressive marketing, no auditing, and secretive behavior by the manager. The firm's demise comes as hedge funds, which are lightly regulated investment vehicles for institutions and wealthy investors, face new SEC registration requirements that have stirred a debate about how much oversight is necessary.Elsewhere in the news today, it was reported that a new miracle drug might cure those addicted to gambling. Do you suppose hedge-fund investors could negotiate a discount if they offered to buy the stuff by the case?
Wednesday, March 08, 2006
If proprietary funds can't make the cut, what's next?
 Today the Riverwalk Golf Club in San Diego hosted the premier sporting event of the year for trust and wealth managers: the ABA Golf Tournament.
Tomorrow, golf bags and plus fours will be out of sight as the 2006 Wealth Management and Trust Conference settles down to business. As in recent years, one high-priority topic will be "open architecture." Clients don't like the idea of being tied to a bank's proprietary funds. Judging from the Conference program, neither do beneficiaries: sometimes they get mad enough to sue.
Citigroup and Merrill Lynch have already sold or spun off their proprietary funds. Major banks are expected to follow suit.
What's next? A recent Barron's cover story (only available to paid subscribers, alas) spotlights separately-managed accounts. Investors in separate accounts own actual stocks, not units of a comingled fund. Separate accounts offer tax-management advantages, plus the opportunity for some customizing, such as no tobacco stocks. SA's can be used as core holdings or, like hedge funds, as niche products.
As of Dec. 31, Barrons's notes, assets in retail separate accounts rose to $678 billion, 18% above the total a year earlier. That surge followed a 16% increase in 2004. Major wirehouses have been the big distributors of separate accounts thus far, but Barron's sees banks gaining a 10% market share by 2010.
Separate accounts tend to have high minimums, though they're coming down. And they tend to be pricey, with average annual expense of 1.7% by one estimate. But these days, even mutual-fund expenses approach 2% on average.
The lower cost alternative? Exchange-traded funds. Independent investment advisers are discovering they can use a handful of ETFs and low-cost bond funds to produce efficient portfolios simply. And annual expense is minimal. Barron's notes that the iShares Russell 3000 (IWV), a popular exchange-traded fund, has an expense ratio of 0.20%.
What's your institution doing?
How wealth managers rebut Buffet
Warren Buffet is a great communicator but an awful poster boy for the premise that investment managers are a waste of money. If you looked at his latest letter to Berkshire-Hathaway shareholders (see previous post), you saw the evidence.
In the long run, like from 1965 through last year, Buffet hasn't just beaten the market, he's trounced and trummeled it:
Berkshire-Hathaway average annual return: 21.5%
S&P 500 average annual return: 10.3%
Buffet's record demonstrates that some people really can produce superior long-term returns,
Can these superior performers be identified? Yes, at least if you're Yale's David Swensen. Over 20 years, the managers he chose for Yale's endowment racked up a 16% annual return.
As long as people like Buffet and Swensen exist, affluent investors will hope for above-average returns. And they'll be willing to pay for investment advice.
In the long run, like from 1965 through last year, Buffet hasn't just beaten the market, he's trounced and trummeled it:
Berkshire-Hathaway average annual return: 21.5%
S&P 500 average annual return: 10.3%
Buffet's record demonstrates that some people really can produce superior long-term returns,
Can these superior performers be identified? Yes, at least if you're Yale's David Swensen. Over 20 years, the managers he chose for Yale's endowment racked up a 16% annual return.
As long as people like Buffet and Swensen exist, affluent investors will hope for above-average returns. And they'll be willing to pay for investment advice.
Monday, March 06, 2006
Wealth managers (and especially Hedge Hogs) receive a Buffeting
When Yale's great investment manager, David Swensen, wrote an earnest but dull book about the high cost of employing generally useless vendors of market-beating techniques, most investors didn't read it.
When John Bogle, Vanguard's patriarch, rants about high investment costs, he draws only limited attention.
But Swensen and Bogle are communications amateurs. The Oracle of Omaha is a pro.
In his letter to Berkshire-Hathaway shareholders, Warren Buffet turns his skills to the subject of "How to minimize your investment returns." Better read it. A lot of your clients and prospects will be reading it, too.
Buffet argues that investors are destined to receive returns substantially below the theoretical averages because they repeatedly shoot themselves in the wallet.
To visualize these self-inflicted wounds, Buffet asks us to imagine that a single family, the Gotrocks, owns every business whose shares are available to investors.
Collectively, the Gotrocks enjoy a return equal to the earnings of their businesses, less taxes. Individually, various members of the Gotrocks clan figure they can do better. So they hire a helper, a broker. When the helper does nothing but cost them money, they hire another helper, a money manager to tell the broker what to buy. And when they realize they're even worse off, they hire a financial planner or consultant to help them pick the right money managers.
What fools these mortals be, says the Oracle:
When John Bogle, Vanguard's patriarch, rants about high investment costs, he draws only limited attention.
But Swensen and Bogle are communications amateurs. The Oracle of
 Omaha is a pro.
In his letter to Berkshire-Hathaway shareholders, Warren Buffet turns his skills to the subject of "How to minimize your investment returns." Better read it. A lot of your clients and prospects will be reading it, too.
Buffet argues that investors are destined to receive returns substantially below the theoretical averages because they repeatedly shoot themselves in the wallet.
To visualize these self-inflicted wounds, Buffet asks us to imagine that a single family, the Gotrocks, owns every business whose shares are available to investors.
Collectively, the Gotrocks enjoy a return equal to the earnings of their businesses, less taxes. Individually, various members of the Gotrocks clan figure they can do better. So they hire a helper, a broker. When the helper does nothing but cost them money, they hire another helper, a money manager to tell the broker what to buy. And when they realize they're even worse off, they hire a financial planner or consultant to help them pick the right money managers.
What fools these mortals be, says the Oracle:
The Gotrocks, now supporting three classes of expensive Helpers, find that their results get worse, and they sink into despair. But just as hope seems lost, a fourth group – we’ll call them the hyper-Helpers – appears. These friendly folk explain to the Gotrocks that their unsatisfactory results are occurring because the existing Helpers – brokers, managers, consultants – are not sufficiently motivated and are simply going through the motions. “What,” the new Helpers ask, “can you expect from such a bunch of zombies?”
The new arrivals offer a breathtakingly simple solution: Pay more money. Brimming with selfconfidence, the hyper-Helpers assert that huge contingent payments – in addition to stiff fixed fees – are what each family member must fork over in order to really outmaneuver his relatives.
The more observant members of the family see that some of the hyper-Helpers are really just manager-Helpers wearing new uniforms, bearing sewn-on sexy names like HEDGE FUND or PRIVATE EQUITY. The new Helpers, however, assure the Gotrocks that this change of clothing is all-important, bestowing on its wearers magical powers similar to those acquired by mild-mannered Clark Kent when he changed into his Superman costume. Calmed by this explanation, the family decides to pay up.
And that’s where we are today: A record portion of the earnings that would go in their entirety to owners – if they all just stayed in their rocking chairs – is now going to a swelling army of Helpers. Particularly expensive is the recent pandemic of profit arrangements under which Helpers receive large portions of the winnings when they are smart or lucky, and leave family members with all of the losses – and large fixed fees to boot – when the Helpers are dumb or unlucky (or occasionally crooked).
Thursday, March 02, 2006
What can you promise new wealth-management clients?
A savvy trust-company exec once told me that affluent investors won't let you manage their money unless you promise them results. That's a problem. Most investment promises aren't worth the hot air required to make them. But the trust-company exec had a solution:
"O.K., I tell the guy. Give us your money to invest, and I promise we'll lose it more slowly than you'd lose it yourself!"
That's still a pretty safe promise to make, according to Mark Hurbert's column in The New York Times:
The Dumb Money pays a significant cost for moving out of stock funds they consider "cold" and moving to those they consider "hot." They probably cut 1% or more off their annual return. And that's in addition to the 1% or more by which managed funds tend to lag the market because of annual fees and expenses.
When you help HNW investors avoid being Dumb Money, you do them a service.
"O.K., I tell the guy. Give us your money to invest, and I promise we'll lose it more slowly than you'd lose it yourself!"
That's still a pretty safe promise to make, according to Mark Hurbert's column in The New York Times:
MOST mutual fund investors have only themselves to blame if their portfolios seriously lag behind the market. That is the conclusion of a new study that says the typical investor has an atrocious sense of timing.Lamont and Frazzini note that some investors do seem to be Smart Money when it comes to picking a hot mutual fund, one that will do well for the next quarter. But in the longer run, "individual investors have a striking ability to do the wrong thing. They send their money to mutual funds which own stocks that do poorly over the subsequent years."
People tend to dump mutual funds just before the funds enter several-year periods of above-average performance, and to buy funds that are about to sag. In fact, the study found that the performance of most fund portfolios would improve markedly if the owners just left well enough alone.
The study, "Dumb Money: Mutual Fund Flows and the Cross-Section of Stock Returns," was conducted by two finance professors, Andrea Frazzini of the University of Chicago and Owen A. Lamont of Yale.
The Dumb Money pays a significant cost for moving out of stock funds they consider "cold" and moving to those they consider "hot." They probably cut 1% or more off their annual return. And that's in addition to the 1% or more by which managed funds tend to lag the market because of annual fees and expenses.
When you help HNW investors avoid being Dumb Money, you do them a service.
Sunday, February 19, 2006
Estate-tax repeal: the backstory
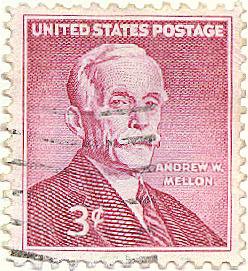 This man put forth a sucessful program for cutting income-tax rates. This man wanted to repeal the estate tax. Who was he? Andrew Mellon, the banker/industrialist turned Treasury Secretary.
You can read all about Mellon's effort, and learn why his aversion to estate taxation was influenced by the settlement of Henry Clay Frick's estate, in this article by Susan Murnane.
Will George W. Bush have better luck than Andrew Mellon had in the 1920‘s? Stay tuned.
Tuesday, February 14, 2006
Easing the Taxpayer's Burden is Expensive
 David G. Klein dreamed up a great illustration for the Sunday New York Times feature on taxes. You can see only a thumbnail here, so I've posted a detail from a scan.
The Times cites projections that the cumulative cost of extending the Bush tax cuts, presumably including repeal of the estate tax, would grow to $1.3 trillion by 2015.
The cumulative “cost” of repealing the Alternative Minimum Tax would also grow to more than $1 trillion.
How do the Administration and Congress get out of this mess? Possibly by taking a serious swing at tax reform. If reform eliminated enough special tax breaks, Congress could vote for lower tax rates in a package that would raise more revenue. But even a “stealth” tax increase is probably too risky to consider before 2007.
Meanwhile, although the federal estate tax exemption has moved up to $2 million. note this warning in another Times article:
In more than a dozen states — including New York, New Jersey, Maine, Maryland, Massachusetts, Minnesota, Kansas, Nebraska, Ohio, Oklahoma, Oregon, Rhode Island and Wisconsin — there are still state taxes on estates worth under $2 million. There is a tax on estates in this range in the District of Columbia, as well.
Monday, February 13, 2006
Death and Taxes: the Blogs
Clever dudes, those guys at The Wall Street Journal. The Blog Watch in today's Technology Report features sites related to one or another of the two inevitables..
Tax sites mentioned include Tax Guru and Roth's Tax Updates.
Inexplicably missing: Joel Schoenmeyer's Death and Taxes — The Blog.
Tax sites mentioned include Tax Guru and Roth's Tax Updates.
Inexplicably missing: Joel Schoenmeyer's Death and Taxes — The Blog.
Monday, February 06, 2006
Could there be some movement on death taxes in 2006?
27 Senators have co-signed a letter asking that a vote on estate tax repeal be scheduled before Memorial Day this year.
Will there be a vote? Probably, there is plenty of polical support, and the House already passed an estate tax repeal. Will the estate tax be repealed? Doubtful, given today's deficits. Could there be a compromise? Certainly, there's plenty of room for a tax regime both sides could live with. But both sides appear to be happier having the fight.
Will there be a vote? Probably, there is plenty of polical support, and the House already passed an estate tax repeal. Will the estate tax be repealed? Doubtful, given today's deficits. Could there be a compromise? Certainly, there's plenty of room for a tax regime both sides could live with. But both sides appear to be happier having the fight.
A potential bomb for CRUTs is defused
Last year, IRS gave estate planners heartburn with Rev. Proc. 2005-24, which discovered a hitherto unknown potential defect in all charitable remainder annuity and unitrusts. The defect was the chance that a surviving spouse might elect a statutory share, that the share might include inter vivos charitable trusts, and so the spouse might ultimately get some assets from the charitable trust. The Service's remedy was to require the spouse to waive such rights, in writing, upon the creation of the trust. Failure to comply would mean no charitable deduction, even if the spouse never ultimately made a claim against the charitable trust.
A variety of problems with this remedy have been voiced by commentators. The snarkier ones have pointed out that IRS' own CRUT and CRAT forms don't address the "problem."
"We hear you," the IRS has now said. Last year's Rev. Proc. had an effective date of June 28, 2005 (earlier-drafted documents were in the clear). In Notice 2006-15 the IRS has now suspended the effective date, and in effect suspended the procedure itself until further guidance is issued. "The Service will disregard the existence of such a right of election, even without a waiver as described in Rev. Proc. 2005-24, but only if the surviving spouse does not exercise the right of election," it concludes. Hopefully future guidance will be more practical.
A variety of problems with this remedy have been voiced by commentators. The snarkier ones have pointed out that IRS' own CRUT and CRAT forms don't address the "problem."
"We hear you," the IRS has now said. Last year's Rev. Proc. had an effective date of June 28, 2005 (earlier-drafted documents were in the clear). In Notice 2006-15 the IRS has now suspended the effective date, and in effect suspended the procedure itself until further guidance is issued. "The Service will disregard the existence of such a right of election, even without a waiver as described in Rev. Proc. 2005-24, but only if the surviving spouse does not exercise the right of election," it concludes. Hopefully future guidance will be more practical.
Which wealth-management clients are you looking for, Comfortable or Kinda Rich?
Here's a wealthy Wall Streeter's guide to the gradations of affluence, as recounted by Lee Eisenberg, author of The Number.
Which market segments are you targeting?
COMFORTABLE
The number
$1-million to $2-million
- A scaled-back lifestyle post-retirement that still includes dining and travelling modestly. A nice life, nonetheless.
COMFORTABLE PLUS
The number
$2-million to $5-million
- A scaled-back lifestyle post-retirement that still includes dining and travelling modestly. Add membership in a mid-priced club and, maybe, a small second home.
KIND OF RICH
The number
$7-million to $10-million
- People who like to stay at the Four Seasons and spend their time shuttling between expensive homes.
RICH
The number
$20-million
- Spend weekends abroad, belong to a gated golf community, charter private jets and party with wealthy people like Henry and Marie-Josee Kravis.
Which market segments are you targeting?
COMFORTABLE
The number
$1-million to $2-million
- A scaled-back lifestyle post-retirement that still includes dining and travelling modestly. A nice life, nonetheless.
COMFORTABLE PLUS
The number
$2-million to $5-million
- A scaled-back lifestyle post-retirement that still includes dining and travelling modestly. Add membership in a mid-priced club and, maybe, a small second home.
KIND OF RICH
The number
$7-million to $10-million
- People who like to stay at the Four Seasons and spend their time shuttling between expensive homes.
RICH
The number
$20-million
- Spend weekends abroad, belong to a gated golf community, charter private jets and party with wealthy people like Henry and Marie-Josee Kravis.
Monday, January 30, 2006
Why the wise wealthy need a corporate trustee
Sunday's New York Times offered an interesting discussion of incentive trusts, the pros and cons.
The article quotes a New York estate-planning attorney who gives sound advice about choosing a trustee:
The article quotes a New York estate-planning attorney who gives sound advice about choosing a trustee:
A trust that offers a dollar for every dollar earned can be unfair, the critics say, because it gives big rewards to already-successful business people and much smaller amounts to heirs who may work just as hard but have chosen careers as, say, artists or teachers. (And unless other provisions are made in the trust, homemakers and volunteers may get nothing.) Critics also say that some incentives may go so far as to pay children to provide their parents with grandchildren.
Treating siblings differently can lead to unintended consequences, said Ralph M. Engel, an estate planning lawyer in the New York City office of Sonnenschein Nath & Rosenthal, based in Chicago. "The problem is that there are too many what-ifs," he said. "What if one sibling can do something and the other can't? What if one becomes disabled or depressed or has an accident?"
Instead, Mr. Engel advises clients to write flexible trusts and to be careful in choosing trustees, who make distribution decisions.
"Pick a trustee who has the guts to say no," he said. Professional trustees, like experienced banks or trust companies, may not be easily swayed by emotional appeals. ***
After 32 years, a royal prince’s estate is finally taxed (and how!)

Queen Elizabeth's uncle, Prince Henry, Duke of Gloucester, was the last royal prince to have his baby picture taken on Queen Victoria's lap. He died in 1974, leaving an estate taxable at the rate (there was a real Labour government in those days, remember) of 75%.
Happily, a “heritage property” election allowed the Duke's executors to defer 75% taxation until the death of Princess Alice, the Duke's widow. She died in 2004, at the age of 102.
To pay the tax, Henry's son, the present Duke, put the family treasures (including Henry's christening present from Queen Victoria) up for auction at Christie's. They fetched a handsome sum, according to this Times of London report.
Read to the end of the Times article, and you also will learn why a Maori war dance was performed in the garden at Kensington Palace.
Tuesday, January 24, 2006
George Foreman on trusts and investing
Quite a guy, George Foreman. Olympic gold medalist, he boxed his way to the world heavyweight championship, retired in 1977 and became a preacher, returned to the ring when his money ran low. In 1994, at age 45, he regained the world championship.
Big George made his really big money hawking George Foreman Electric Grills, initially for 40% of the profits. In 1999 he sold the rights to his name for $127.5 million in cash plus $10 million of stock in the grill-maker, Salton Inc.
In a recent Wall Street Journal interview, Foreman talked a bit about money matters. A few excepts:
On why one of his best investments was a trust
When I first started making money from boxing, I put 25% of all my earnings into a trust fund. I made other investments during that time, in cattle and gas wells, that I lost my shirt on, but I always had the trust fund. When I retired to become a minister, I survived on that money. I learned how important it is to have something to fall back on.
On his reaction as an investor to 9/11
After 9/11 . . . I took a lot of money and told my broker to buy American company stocks. He said, "Don't you want to wait?" and I said "No, this happened to New York for a reason, to scare us." That investment paid off greatly.
On his asset allocation
I have about 35% invested in stocks, about 35% in bonds and the rest in real estate. I like investing in real estate, it's first in my heart. I've bought and sold a lot of property all over the country. I have a ranch in east Texas that I particularly love and will keep until I pass. Then maybe my children can cash it in.
On obtaining investment advice
I have a lot of people who help me, but I've known from my boxing days that you should never rely on just one person. You must be diverse in the information you receive. Because investors are just like boxers, they get punch-drunk, they get burned out, and no one knows it until their legs start wiggling.
On his best investment
I still believe my best investment has been...the money I put into universities [to fund scholarships]. I never call them donations, I call them investments.
Big George made his really big money hawking George Foreman Electric Grills, initially for 40% of the profits. In 1999 he sold the rights to his name for $127.5 million in cash plus $10 million of stock in the grill-maker, Salton Inc.
In a recent Wall Street Journal interview, Foreman talked a bit about money matters. A few excepts:
On why one of his best investments was a trust
When I first started making money from boxing, I put 25% of all my earnings into a trust fund. I made other investments during that time, in cattle and gas wells, that I lost my shirt on, but I always had the trust fund. When I retired to become a minister, I survived on that money. I learned how important it is to have something to fall back on.
On his reaction as an investor to 9/11
After 9/11 . . . I took a lot of money and told my broker to buy American company stocks. He said, "Don't you want to wait?" and I said "No, this happened to New York for a reason, to scare us." That investment paid off greatly.
On his asset allocation
I have about 35% invested in stocks, about 35% in bonds and the rest in real estate. I like investing in real estate, it's first in my heart. I've bought and sold a lot of property all over the country. I have a ranch in east Texas that I particularly love and will keep until I pass. Then maybe my children can cash it in.
On obtaining investment advice
I have a lot of people who help me, but I've known from my boxing days that you should never rely on just one person. You must be diverse in the information you receive. Because investors are just like boxers, they get punch-drunk, they get burned out, and no one knows it until their legs start wiggling.
On his best investment
I still believe my best investment has been...the money I put into universities [to fund scholarships]. I never call them donations, I call them investments.
Monday, January 23, 2006
Please don't leave me a million!
Trusts are trendy, as we noted recently. Today's example, Karen Hube's discussion of disclaimers in the Wall Street Journal. She puts in a good word for GSTs:
If your benefactor is still alive, the most drastic option is simply to request to be left out of a will. Before going that route, however, you should consider a more flexible, if complicated, alternative: You can ask that the benefactor, rather than naming you directly as an heir, instead establish a "generation-skipping trust" -- one that names your children as the beneficiaries.Question is, how rich does someone have to be in order to feel comfortable with the idea of saying “please don't leave me a million"? Surveys suggest that even someone with $10 million believes he or she would be more secure with more substantial wealth.
Such an arrangement offers several benefits. First, if the need ever arises, you can draw income from the trust, even though you don't own the assets outright. Second, because you don't own the assets, the property avoids estate taxes when you die. Finally, any assets that your children don't tap during their lifetimes can be passed to the subsequent generation free of all but income taxes. If you don't have children, a generation-skipping trust can be set up for another member of the younger generation in your family -- say, a niece or a nephew.
Saturday, January 21, 2006
Trust of the Month for "transhumans:" The PRT
You can't take it with you, but you can come back and get it, as Wall Street Journal readers learn today from this article.
PRT stands for Personal Revival Trust. Perhaps a dozen or more have been set up. Here's how grantors like David Pizer of Arizona hope to leave millions to . . . themselves!
PRT stands for Personal Revival Trust. Perhaps a dozen or more have been set up. Here's how grantors like David Pizer of Arizona hope to leave millions to . . . themselves!
Like some 1,000 other members of the "cryonics" movement, Mr. Pizer has made arrangements to have his body frozen in liquid nitrogen as soon as possible after he dies. In this way, Mr. Pizer, a heavy-set, philosophical man who is 64 years olThe Journal reports that Wachovia is trustee of at least one PRT. A Wachovia estate planner recently discussed the concept at the First Annual Colloquium on the Law of Transhuman Persons in Florida.d, hopes to be revived sometime in the future when medicine has advanced far beyond where it stands today.
And because Mr. Pizer doesn't wish to return a pauper, he's taken an additional step: He's left his money to himself.
With the help of an estate planner, Mr. Pizer has created legal arrangements for a financial trust that will manage his roughly $10 million in land and stock holdings until he is re-animated. Mr. Pizer says that with his money earning interest while he is frozen, he could wake up in 100 years the "richest man in the world."

Trust of the Month: The QPRT
Thanks to this New York Times article, a lot of trust clients and prospects should be asking about Qualified Personal Residence Trusts.
Does anyone care to comment on how QPRTs work out in practice?
If a house passes to several children, for instance, do they easily agree on what to do with the real estate?
If the parents stay on as renters after the end of the QPRT term, are the kids willing to spend some of the rent on maintaining the place in the manner to which the parents have been accustomed? Or do the parents simply keep paying for upkeep, looking at the payments as added "wealth transfers"?
Does anyone care to comment on how QPRTs work out in practice?
If a house passes to several children, for instance, do they easily agree on what to do with the real estate?
If the parents stay on as renters after the end of the QPRT term, are the kids willing to spend some of the rent on maintaining the place in the manner to which the parents have been accustomed? Or do the parents simply keep paying for upkeep, looking at the payments as added "wealth transfers"?
Wednesday, January 18, 2006
“A startling new retirement-planning need”
Ameriprise (the old IDS that recently severed ties with American Express) has sponsored a new study of retirement.
Most interesting finding: People nearing or in retirement worry a lot about their children's lack of financial savvy.
Coddling could be one reason. The study reports that the number of households with children over age 18 living at home increased by 69% from 2000 to 2004! Also, Boomers tend to feel they've been poor role models when it comes to demonstrating financial responsibility.
I can think of a couple of other reasons for parental worry:
• Couples who delayed having children are more likely to retire before their kids mature.
• Today's young adults tend to carry a far higher debt burden, student loans and credit-card debt, that built up during their college years.
The Ameriprise study, conducted by Ken Dychtwald and Harris Interactive, also reveals regional differences. Westerners, it seems, are more likely to prepare for retirement than easterners.
Most interesting finding: People nearing or in retirement worry a lot about their children's lack of financial savvy.
Coddling could be one reason. The study reports that the number of households with children over age 18 living at home increased by 69% from 2000 to 2004! Also, Boomers tend to feel they've been poor role models when it comes to demonstrating financial responsibility.
I can think of a couple of other reasons for parental worry:
• Couples who delayed having children are more likely to retire before their kids mature.
• Today's young adults tend to carry a far higher debt burden, student loans and credit-card debt, that built up during their college years.
The Ameriprise study, conducted by Ken Dychtwald and Harris Interactive, also reveals regional differences. Westerners, it seems, are more likely to prepare for retirement than easterners.
Monday, January 16, 2006
Why Apple is golden
 Last spring the first post on the Trust and Wealth Management Marketing blog concerned Apple computer. So it's none too soon to go slightly off-topic again.
For Christmas your Senior Assistant Blogger received an iPod. Not a video one, not even a Nano. Just a big, old, monochrome-screen iPod. I was expecting something clunky. Instead, there in my hand was a white-and-silver art object of surpassing beauty, demanding to be caressed and cherished. Wow!
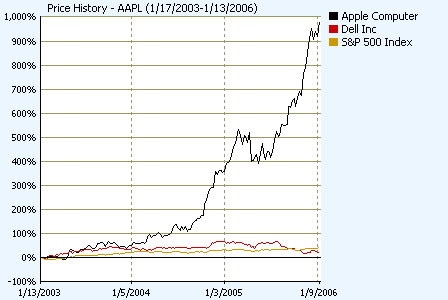
Now I see why Apple's market value has soared past Dell's. And why Jonathan Ive, the London-born designer of the iPod, was just honored by his Queen.
The lesson of the iPod, I guess, is that sometimes form is function, and I'm not sure how that applies to marketing financial services. But I do detect a useful reminder in Steve Jobs’ successful marketing of Macintosh computers.
The new "Intel inside" iMacs Steve announced last week run twice as fast as the previous G5 model. The new MacBook laptop is said to run four or five times as fast as the G4 Powerbook it replaces. Yet it wasn't that long ago that Steve was tweaking test statistics to demonstrate that the old models were just as fast as Intel PCs for practical purposes. And the old models were so cool, so convenient and relatively reliable to use, that folks were willing to believe the hyperbole. Macs survived and began to prosper.
Reminds me of our old friend Knute Alphanot, at Lake Woebegone B&T. His trust department's investment performance is never more than mediocre (though rarely less than). But Knute has a winning way of adjusting his returns for volatility, currency fluctuations, and maybe even windage. By the time he's through, he can show his clients he's always above average. Top Quartile, usually.
OK, maybe most of the clients don't believe him. But as many a consultant has pointed out, you can get away with merely decent investment performance if you do the very best you can for your clients in all other respects. Knute's department runs like a Rolex, and client communications — from thoughtful notes and phone calls to newsletters and seminars — are never neglected.
Moral: You don't need great investment returns as long as you offer your clients insanely great service. Make them feel as cherished as . . . an iPod!
P.S. I hope your investment people bought Apple, not Dell!
Notes on the Heckerling Institue
The last time I went to this conference was more than 20 years ago, and it was then always known as the Miami Institute. It’s been renamed the Heckerling Institute since then, and it long ago outgrew the facilities at Bar Harbor. This year saw some 2,600 registrants. I think that $850 is a tremendous bargain for a five-day conference, but on the other hand at these volumes they collect $2.2 million in registration fees.
The main lecture hall seated, by my rough estimate, 2,000 people, which, although enormous, was inadequate. So there were two large video overflow halls. They had three tripod-mounted video cameras aimed at the podium that seemed to have servo motors to permit remote adjustment. Someone was flipping among the three images as appropriate, and the video was simulcast on enormous screens, two in the main hall and one in each of the overflow rooms. The video was so good I found myself watching it instead of the speaker, even when I was in the main room.
With so many attendees, a second hotel was pressed into service, about 1/4 mile away, and shuttles ran between the two hotels. With a crowd this large, the breakout sessions require rooms that can seat 500 people, and the Fontainebleau didn’t have enough rooms of that size, so some of the breakouts were held at the other hotel.
Finally, the main sessions were simulcast into the individual rooms in both hotels, so one didn’t have to rush down to see any of the presentations. And in fact, many didn’t, because although the rooms always seemed full, they never seemed crowded, approaching their capacity.
Because of this fact, and the split between the two hotels, one of the exhibitors I spoke with complained that although registration might be up, her traffic was down. That’s another thing that changed dramatically in 20 years, the vendor list is at about 120, with 146 booth spaces (about 25 used double wide booths). The booths cost $2,000 each this year, so that’s another $300,000 into the kitty.
Lots of banks exhibit, including many of our customers. DB was there, distributing the high-end newsletter that we just bid on, as was Harris, Wachovia, Bank of America, Northern Trust, HSBC, Citibank, others that aren’t popping into my head now. I have the vendor list.
The banks consistently said that they were trying to get referrals from estate planners for the full range of their private wealth management services, and so were there to network. However, the B of A guy made the additional observation that “we want to be exposed to the talent that comes here.” They want relationships with a strong, nationwide network of attorneys. If someone in Connecticut is going to relocate to Arizona, B of A wants their Connecticut banker to be able to give the client the name and number of a recommended Arizona attorney with whom to make contact. If they have this network, they should communicate with it on a regular basis, and that validates the custom newsletter pitch that we made to them about a year ago.
The pace over five days was not relaxed, but neither was it hectic. We started each day at 9, after a one-hour breakfast in the exhibit area. Each day included 1 3/4 hours for lunch, with sandwiches for sale in the exhibit area, and nothing was scheduled in the evenings (program ended at 5:15). That’s to allow for massive schmoozing. The vendors sponsored lunches for their favored planners in the hotel, typically with a speaker (Mass Mutual did one on special needs trusts, for example). They also invited selected participants to social outings in the evenings.
The final big change is that Continuing Legal Education requirements help to drive professionals to this program. More than one attorney mentioned to me that this one conference took care of his requirements for the full year. CLE is also required for the insurance guys, and they typically have to sign in for each session to prove their attendance.
In case some people have trouble transitioning away from the “Miami Institute” name, next year the conference will be in Orlando (the next three years, actually) at the Mariott World Center or something like that. Happily, the whole thing then will happen under one roof, because it is a significantly bigger facility. Plus, and this is key I suspect, it has a bigger exhibition hall. They tentatively expect that the proximity to Disney World ($5 cab ride, but no shuttle connection) will boost attendance by 10%, as families make a big vacation out of it. Some of the vendors, however, wonder if the old timers who always go to the program in Miami will really follow it to Orlando. Only time will tell.
Key estate planning issues
I was pleased to learn that Merrill Anderson has stayed well on top of the most critical issues of concern to estate planners. Number one on that list is the decoupling of state and federal taxes, which has been far more complicated than anyone every expected. I suspect that they were all shocked that any states allowed their death taxes to lapse, but 33 have. In addition, we now have “super-decoupling,” which means that not only do some states rely on the pre-2001 federal credit for state death taxes, they have independent exemption amounts. $1 million seems most common, which creates a big dilemma for the $5 million or so estate. To claim the full federal exempt amount requires payment of a state death tax of probably $100,000 or so. A few states have resolved this with the addition of a state-law based QTIP election. It gets really complicated.
What’s more, some states don’t have a gift tax, and rely on the old federal credit for state death taxes. Trouble is, the federal credit doesn’t take lifetime gifts into account (it comes in before the adjusted taxable gifts are added in to determine the tax rate). Bottom line: In the state of Virginia for sure (and probably many others), if one makes a deathbed gift of one’s entire estate, the state death tax is reduced to nothing (but there’s no effect on federal tax liability). Sounds wild, but it has been happening, and it works.
Item two is the shifting federal tax law, and planners’ growing impatience over getting a resolution. There is strong sentiment for killing carryover basis, there is an expectation that rates may be brought way down, to the 15% or 20% range. The one-year repeal is intensely unpopular, but it remains a serious possibility, given the rising tide of partisanship in DC. One school of thought says that 2005 was the year for transfer tax compromise. 2006 is an election year for Congress, and the next Presidential contest will be starting in 2007, making tax reform that much more difficult. On the other hand, the biggest tax reform perhaps in US history happened in 1986, which was a Congressional election year.
The final big item on the agenda (everything else seemed second tier to me, although there was also a ton of talk about FLPs and the Strangi case) was Circular 230. There is tremendous fear and loathing over this. I went to a breakout session on it, and I heard Roy Adams speak on it from the podium.
Roy believes that the sky is falling rapidly. He believes that the club IRS has raised is real, will be very hard to deal with, and that practitioners will have to pay close attention. On the other hand, he acknowledges that some of the routine estate planning advice given out by lawyers may be protected by one of the several exceptions to the new rules. However, on Roy’s reading of the requirements I would guess that FLPs are pretty much history, because they will require a “covered opinion letter” which Roy thinks will be so expensive to create that only the super rich can afford them.
Lou Mezzulo, on the other hand, is not so very worried (though he is concerned). He doesn’t believe that any of his written communications fall within the new requirements, because in all cases the primary purpose of his advice is not how to avoid taxes but how to pass property to the next generation (albeit on a tax-efficient basis). Even FLP communications are safe, in his analysis, because the big issue—their estate inclusion based upon IRC 2036—is determined not by his advice or the documents he drafts, but by the client’s subsequent conduct. Mezzulo said that he has not once included the 230 disclaimer on any of his client correspondence. Roy didn’t say, but I’m pretty confident that he uses a disclaimer with some regularity. However, clients tend to be upset when they read that they can’t rely upon advice for which they have paid good money.
It’s clear that Circular 230 doesn’t apply to our newsletters, which are in the nature of a treatise and not advice to specific clients. It’s equally clear that newsletter publishers are ignoring this reality and putting 230 disclaimers on their products anyway.
Conclusion
One thing is clear: Estate planning is not going away. Banks continue to recognize it as a hot button and entry path to the high net worth market. Planners are preparing for a life without the estate tax to goad people into action, and they are concerned about that. Lawyers pay more for their direct mail than bankers or brokers pay. And evidently, the public continues to have a thirst for estate planning information.
The conference was a great experience, and I should not wait 20 years before going again.
The main lecture hall seated, by my rough estimate, 2,000 people, which, although enormous, was inadequate. So there were two large video overflow halls. They had three tripod-mounted video cameras aimed at the podium that seemed to have servo motors to permit remote adjustment. Someone was flipping among the three images as appropriate, and the video was simulcast on enormous screens, two in the main hall and one in each of the overflow rooms. The video was so good I found myself watching it instead of the speaker, even when I was in the main room.
With so many attendees, a second hotel was pressed into service, about 1/4 mile away, and shuttles ran between the two hotels. With a crowd this large, the breakout sessions require rooms that can seat 500 people, and the Fontainebleau didn’t have enough rooms of that size, so some of the breakouts were held at the other hotel.
Finally, the main sessions were simulcast into the individual rooms in both hotels, so one didn’t have to rush down to see any of the presentations. And in fact, many didn’t, because although the rooms always seemed full, they never seemed crowded, approaching their capacity.
Because of this fact, and the split between the two hotels, one of the exhibitors I spoke with complained that although registration might be up, her traffic was down. That’s another thing that changed dramatically in 20 years, the vendor list is at about 120, with 146 booth spaces (about 25 used double wide booths). The booths cost $2,000 each this year, so that’s another $300,000 into the kitty.
Lots of banks exhibit, including many of our customers. DB was there, distributing the high-end newsletter that we just bid on, as was Harris, Wachovia, Bank of America, Northern Trust, HSBC, Citibank, others that aren’t popping into my head now. I have the vendor list.
The banks consistently said that they were trying to get referrals from estate planners for the full range of their private wealth management services, and so were there to network. However, the B of A guy made the additional observation that “we want to be exposed to the talent that comes here.” They want relationships with a strong, nationwide network of attorneys. If someone in Connecticut is going to relocate to Arizona, B of A wants their Connecticut banker to be able to give the client the name and number of a recommended Arizona attorney with whom to make contact. If they have this network, they should communicate with it on a regular basis, and that validates the custom newsletter pitch that we made to them about a year ago.
The pace over five days was not relaxed, but neither was it hectic. We started each day at 9, after a one-hour breakfast in the exhibit area. Each day included 1 3/4 hours for lunch, with sandwiches for sale in the exhibit area, and nothing was scheduled in the evenings (program ended at 5:15). That’s to allow for massive schmoozing. The vendors sponsored lunches for their favored planners in the hotel, typically with a speaker (Mass Mutual did one on special needs trusts, for example). They also invited selected participants to social outings in the evenings.
The final big change is that Continuing Legal Education requirements help to drive professionals to this program. More than one attorney mentioned to me that this one conference took care of his requirements for the full year. CLE is also required for the insurance guys, and they typically have to sign in for each session to prove their attendance.
In case some people have trouble transitioning away from the “Miami Institute” name, next year the conference will be in Orlando (the next three years, actually) at the Mariott World Center or something like that. Happily, the whole thing then will happen under one roof, because it is a significantly bigger facility. Plus, and this is key I suspect, it has a bigger exhibition hall. They tentatively expect that the proximity to Disney World ($5 cab ride, but no shuttle connection) will boost attendance by 10%, as families make a big vacation out of it. Some of the vendors, however, wonder if the old timers who always go to the program in Miami will really follow it to Orlando. Only time will tell.
Key estate planning issues
I was pleased to learn that Merrill Anderson has stayed well on top of the most critical issues of concern to estate planners. Number one on that list is the decoupling of state and federal taxes, which has been far more complicated than anyone every expected. I suspect that they were all shocked that any states allowed their death taxes to lapse, but 33 have. In addition, we now have “super-decoupling,” which means that not only do some states rely on the pre-2001 federal credit for state death taxes, they have independent exemption amounts. $1 million seems most common, which creates a big dilemma for the $5 million or so estate. To claim the full federal exempt amount requires payment of a state death tax of probably $100,000 or so. A few states have resolved this with the addition of a state-law based QTIP election. It gets really complicated.
What’s more, some states don’t have a gift tax, and rely on the old federal credit for state death taxes. Trouble is, the federal credit doesn’t take lifetime gifts into account (it comes in before the adjusted taxable gifts are added in to determine the tax rate). Bottom line: In the state of Virginia for sure (and probably many others), if one makes a deathbed gift of one’s entire estate, the state death tax is reduced to nothing (but there’s no effect on federal tax liability). Sounds wild, but it has been happening, and it works.
Item two is the shifting federal tax law, and planners’ growing impatience over getting a resolution. There is strong sentiment for killing carryover basis, there is an expectation that rates may be brought way down, to the 15% or 20% range. The one-year repeal is intensely unpopular, but it remains a serious possibility, given the rising tide of partisanship in DC. One school of thought says that 2005 was the year for transfer tax compromise. 2006 is an election year for Congress, and the next Presidential contest will be starting in 2007, making tax reform that much more difficult. On the other hand, the biggest tax reform perhaps in US history happened in 1986, which was a Congressional election year.
The final big item on the agenda (everything else seemed second tier to me, although there was also a ton of talk about FLPs and the Strangi case) was Circular 230. There is tremendous fear and loathing over this. I went to a breakout session on it, and I heard Roy Adams speak on it from the podium.
Roy believes that the sky is falling rapidly. He believes that the club IRS has raised is real, will be very hard to deal with, and that practitioners will have to pay close attention. On the other hand, he acknowledges that some of the routine estate planning advice given out by lawyers may be protected by one of the several exceptions to the new rules. However, on Roy’s reading of the requirements I would guess that FLPs are pretty much history, because they will require a “covered opinion letter” which Roy thinks will be so expensive to create that only the super rich can afford them.
Lou Mezzulo, on the other hand, is not so very worried (though he is concerned). He doesn’t believe that any of his written communications fall within the new requirements, because in all cases the primary purpose of his advice is not how to avoid taxes but how to pass property to the next generation (albeit on a tax-efficient basis). Even FLP communications are safe, in his analysis, because the big issue—their estate inclusion based upon IRC 2036—is determined not by his advice or the documents he drafts, but by the client’s subsequent conduct. Mezzulo said that he has not once included the 230 disclaimer on any of his client correspondence. Roy didn’t say, but I’m pretty confident that he uses a disclaimer with some regularity. However, clients tend to be upset when they read that they can’t rely upon advice for which they have paid good money.
It’s clear that Circular 230 doesn’t apply to our newsletters, which are in the nature of a treatise and not advice to specific clients. It’s equally clear that newsletter publishers are ignoring this reality and putting 230 disclaimers on their products anyway.
Conclusion
One thing is clear: Estate planning is not going away. Banks continue to recognize it as a hot button and entry path to the high net worth market. Planners are preparing for a life without the estate tax to goad people into action, and they are concerned about that. Lawyers pay more for their direct mail than bankers or brokers pay. And evidently, the public continues to have a thirst for estate planning information.
The conference was a great experience, and I should not wait 20 years before going again.
Sunday, January 15, 2006
For safety's sake, choose a corporate trustee
Corporate trustees may not be perfect, but more than $1 trillion has been entrusted to their care for good reason.
Corporate safeguards protect trust funds from the temptations to which the flesh is heir to. And if these safeguards fail, the corporate entity usually has the resources to replace what its employee stole.
Here's a case, chronicled in The New York Times, where a “disinguished” individual trustee succumbed to temptation to the tune of $400,000.
“‘I don't think he feels like he did anything wrong,’ said Karen Dove, a guardian for Mr. Amundson's victim.”
Corporate safeguards protect trust funds from the temptations to which the flesh is heir to. And if these safeguards fail, the corporate entity usually has the resources to replace what its employee stole.
Here's a case, chronicled in The New York Times, where a “disinguished” individual trustee succumbed to temptation to the tune of $400,000.
Until 2001, [Roland] Amundson, 56, was a highly regarded judge who sat on the Minnesota Court of Appeals, the state's second-highest court.Admundson is due to be released from confinement almost two years early. Not everyone thinks that's a good idea:
Mentioned in legal circles as a likely nominee to the State Supreme Court, he was a popular public speaker, served on charitable boards in Minneapolis, and seemed to know everyone. Colleagues described him as brilliant and charming.
Then he was caught taking $400,000 from a trust fund he oversaw for a woman with the mental capacity of a 3-year-old, money he spent on marble floors and a piano for his house as well as model trains, sculpture and china service for 80, all bought on eBay.
“‘I don't think he feels like he did anything wrong,’ said Karen Dove, a guardian for Mr. Amundson's victim.”
Thursday, January 05, 2006
Financial Newsletters Really Work!
Of course at Merrill Anderson we've always said that newsletters provide results (even if the results are hard to quantify) but now we have independent verification. This article,Newsletter News: An informal survey of advisers shows that there are many reasons to have a newsletter. (registration required), reports that in an informal survey of fee-only and fee-based independed advisors, 72% said that having a newsletter "was an important part of their business building efforts." 65% mail quarterly, 13% monthly, the rest on some other basis.
What does a newsletter accomplish? The respondents say what we've long said at Merrill Anderson:
* Client communication and retention
* Visibility strategy
* Credibility building (reputation)
* Deliver planning and investment education
* Reinforce investment and business philosophies
* Create new business.
I love getting that third party validation.
What does a newsletter accomplish? The respondents say what we've long said at Merrill Anderson:
* Client communication and retention
* Visibility strategy
* Credibility building (reputation)
* Deliver planning and investment education
* Reinforce investment and business philosophies
* Create new business.
I love getting that third party validation.
Monday, January 02, 2006
Who busted my three-legged stool?
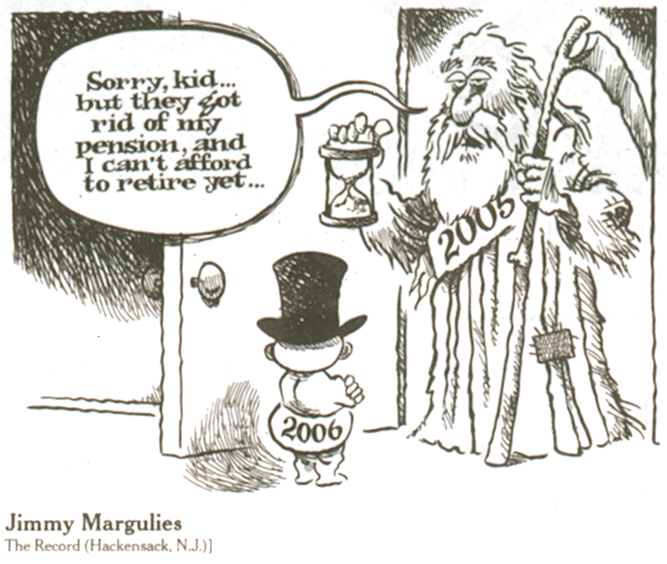
Remember when financial security during retirement rested on a three-legged stool?
One leg, Social Security, is shaky but doesn't matter too much to the HNW market.
The second leg, pensions, is another matter. Many highly-paid executives count on funded and unfunded employer pensions to help support a jet-set retirement lifestyle.
With pensions in jeopardy, that leaves personal savings and investments to carry the retirement load.
Sounds like professional wealth management is a must, wouldn't you say?
Tuesday, December 27, 2005
Looks like a Happy New Year for trust marketers!
Trusts are trendy, according to Rachel Emma Silverman's article in the Christmas Eve edition of The Wall Street Journal.
Assets in personal trusts nearly doubled from 1998 through 2004, soaring to $1.19 trillion.
And that estimate may be low. Corporate trustees alone held more than $1 trillion in personal trusts last year, according to the American Bankers Association.
Driving the trend to trusts, Silverman writes, are the Baby Boomers, now reaching an age when thoughts of wealth-preservation and estate planning begin to be thought.
Not only are more trusts being set up, more are likely to last an heir's lifetime:
Assets in personal trusts nearly doubled from 1998 through 2004, soaring to $1.19 trillion.
And that estimate may be low. Corporate trustees alone held more than $1 trillion in personal trusts last year, according to the American Bankers Association.
Driving the trend to trusts, Silverman writes, are the Baby Boomers, now reaching an age when thoughts of wealth-preservation and estate planning begin to be thought.
Not only are more trusts being set up, more are likely to last an heir's lifetime:
Traditionally, many parents would leave money to their children either directly, or would create short-term trusts that would pay out when the kids reached specific ages -- say, some disbursed when a child reaches 25 years old, then more at 30, then 35 -- after which point, the trusts would dissolve.As more trusts last longer, Silverman notes, they have become more flexible. Corporate trustees will be challenged to redefine the role of trustee: no longer merely working for the heirs but working with them.
But in recent years, more lawyers have advised parents to leave gifts or inheritances, even small ones, in long-term trusts. The idea is that money left in trust for as long as possible is safer -- from creditors, divorcing spouses and estate taxes -- than money given outright.
Tuesday, December 20, 2005
Here We Come A-Gifting
 In the Holiday Spirit, we come bearing gifts, chosen in the knowledge that it's the thought that counts.
• For active portfolio managers, who keep forgetting that hyperactive turnover usually leads to underperformance, a relaxing mug of hot mulled cider.
• For indexers, who need a way to keep awake while their passive portfolios outperform most actively-managed funds, a Starbucks Gift Certificate.
• For hedge fund honchos, who know it's "positive returns or perish," a year's supply of 100-proof Alpha (take only as directed).
• For tax practitioners, the prospect of a new round of Tax Reform. (And you can bet that Congress, once again, will make a glorious mess of it.)
• For trust and wealth-management marketers, a new batch of HNW Hot Buttons. ready to be pushed.
To all, best wishes for a Christmas that is Merry, a Hannakuh that is Blessed, a Yule that is Wicked Cool!
Tuesday, December 13, 2005
Rich kids need to be carefully taught
As noticed in the preceding posts, Sir Tom Hunter and Mr. Andrew Carnegie advise the New Rich to give their billions away, not heap it upon their kids.
Not all wealthy parents like that advice. What's more, even the few millions one might leave to a son or daughter as a modest life endowment could easily look like making-whoopee money to an untutored young person.
Hence the growing emphasis on helping ultra-high-net-worth parents teach their potential heirs to be self reliant and financially literate. For a discussion of this subject recently commissioned by Northern Trust, see Preparing Children for a Life of Wealth.
This week, by the way, Northern's web site announces a nice honor. Private Banking International magazine has selected Northern Trust as the winner of the Outstanding Private Bank—The Americas Award 2005.
Not all wealthy parents like that advice. What's more, even the few millions one might leave to a son or daughter as a modest life endowment could easily look like making-whoopee money to an untutored young person.
Hence the growing emphasis on helping ultra-high-net-worth parents teach their potential heirs to be self reliant and financially literate. For a discussion of this subject recently commissioned by Northern Trust, see Preparing Children for a Life of Wealth.
This week, by the way, Northern's web site announces a nice honor. Private Banking International magazine has selected Northern Trust as the winner of the Outstanding Private Bank—The Americas Award 2005.
Saturday, December 10, 2005
Tom Hunter: “almost accidental philanthropist”
Andrew Carnegie (see preceding post) has a new disciple — and a Scot, to boot!
Alan Cowell profiles Tom Hunter in today's New York Times:
 rable fortune.
Alan Cowell profiles Tom Hunter in today's New York Times:
When Tom Hunter says he plans to get serious about something, he seems to mean it. Earlier this year, after touring Africa with former President Bill Clinton , Mr. Hunter - now Sir Tom - resolved to get serious about philanthropy for a continent in turmoil. The result? A promise of $100 million, ponied up for projects to wrest Africans from poverty - not bad for a man of 44 who started off his business career with borrowed money, selling sneakers.Son of a greengrocer, Hunter borrowed from his family to start a chain of sneakers stores. Seven years ago he cashed in, selling his Sports Division chain for a conside
 rable fortune.
When they first became rich, in 1998, Sir Tom said, he and his wife, Marion, formed a charitable trust because it was "tax efficient," making him almost an accidental philanthropist. Then, becoming frustrated with some of his early giving in Scotland, he turned for advice to Vartan Gregorian, the president of the Carnegie Corporation of New York, a choice of guru that reflected his reverence for the Scottish-born forefather of American philanthropy, Andrew Carnegie.Sir Tom has plenty of room for more philanthropy before he gets to "nothing." He ranked sixty-ninth on last spring's Sunday Times Rich List.
Indeed, Sir Tom likes to quote Andrew Carnegie, saying, "He who dies thus rich dies disgraced." He matches that adage with a public vow of his own, made in a recent speech: "I would leave this world as we came into it, with nothing. My family and kids would be well looked after but would not be burdened by the challenge of managing phenomenal wealth." ("My kids like to debate that," he added.)
Friday, December 09, 2005
How to keep wealthy clients alive and happy
Money sometimes does make people happy, according to Syracuse professor Arthur Brooks writing in The Wall Street Journal.
Five years ago, Metcalf and Merida met wealth head on, sharing a $34 million lottery jackpot.
Wealth acquired more conventionally isn't necessarily fatal but, as Ruth Marcus writes in the Washington Post, the wretched excesses of the new Gilded Age are not a pretty sight:
Back in the original Gilded Age, one of the most passionate critics of wretched excess was Andrew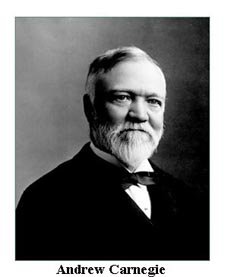 Carnegie. Above and beyond the "competence" needed to live in independence and comfort, Carnegie believed wealth should be used for the public good. This charitable work, he insisted, should be done during the wealth-builder's lifetime, not by bequest:
According data from surveys by the National Opinion Research Center, for example, people in the top fifth of income earners are about 50% more likely to say they are "very happy" than people in the bottom fifth, and only about half as likely to say they are "not too happy."In large, sudden doses, unfortunately, money can make people dead. A December 5 New York Times article reports on the short, unhappy lives of Mack W. Metcalf, a Kentucky forklift driver, and his estranged second wife, Virginia Merida, the daughter of a drug dealer.
There is, however, generally very little change in the average level of happiness in populations getting richer over the years. For instance, the percentage of the U.S. population saying it was "very happy" in 1972 was exactly the same as it was in 2002: 30.3%. Social critics of "consumerism" explain this by claiming that what makes rich people happy is not money per se, but rather the fact that they have more of it than others . . . .
Five years ago, Metcalf and Merida met wealth head on, sharing a $34 million lottery jackpot.
Years of blue-collar struggle and ramshackle apartment life gave way almost overnight to limitless leisure, big houses and lavish toys. Mr. Metcalf bought a Mount Vernon-like estate in southern Kentucky, stocking it with horses and vintage cars. Ms. Merida bought a Mercedes-Benz and a modernistic mansion overlooking the Ohio River, surrounding herself with stray cats.Three years later, Metcalf was dead of complications relating to alcoholism. On the day before Thanksgiving, Merida's decomposing body was found; authorities suspect death by drug overdose. Only hint of a silver lining: $500,000 was salvaged to create a trust fund for Metcalf's daughter by his first marriage.
Wealth acquired more conventionally isn't necessarily fatal but, as Ruth Marcus writes in the Washington Post, the wretched excesses of the new Gilded Age are not a pretty sight:
Washington, of course, has always had its moneyed denizens . . . . What's different about Washington in this latest Gilded Age is the amount of money sloshing around this city -- this region, actually -- and the ostentatious display thereof . . .
The result is a strange version of increasing income inequality . . .The wretched excesses of the former American University president and his wife, for instance, can be attributed in part to their constant proximity to wealthy donors and immersion in Washington's social scene. If everyone else is having their drivers take them to the luncheon with the ambassador's wife, how could Nancy Ladner drive her own car -- even if it was a black 2003 Infiniti Q45? If everyone else has a private chef, why not have yours create a 13-course dinner to celebrate your son's engagement? Why not start with White Truffle & Porcini Egg Custard & American Sturgeon Caviar?
Back in the original Gilded Age, one of the most passionate critics of wretched excess was Andrew
 Carnegie. Above and beyond the "competence" needed to live in independence and comfort, Carnegie believed wealth should be used for the public good. This charitable work, he insisted, should be done during the wealth-builder's lifetime, not by bequest:
Knowledge of the results of [charitable] legacies bequeathed is not calculated to inspire the brightest hopes of much posthumous good being accomplished. The cases are not few in which the real object sought by the testator is not attained, nor are they few in which his real wishes are thwarted. In many cases the bequests are so used as to become only monuments of his folly.Professor Brooks tells us why you should take Carnegie's point seriously: "Donating money (and time) is one of the best ways to buy happiness."
People who donate to charity are 40% more likely to say they are "very happy" than non-donors. Psychologists have even tested whether charity makes people happy using randomized, controlled experiments -- the same procedure used for testing pharmaceuticals, except that, instead of administering a drug to one group and a placebo to the other, researchers randomly assign one group to act charitably toward another. The results are clear: Givers of charity earn substantial mental and physical health rewards, even more than do the recipients of charity -- empirical evidence that it is indeed more blessed to give than to receive.Ready to help your clients help themselves to happiness? Then get to work on those charitable trusts, family foundations and donor-advised funds!
Tuesday, November 29, 2005
Will review: bad news and good news
How do you hold on to will appointments when your institution has been acquired by Engulf & Devour Bank and Trust? If you are now working for E&D, today's Wall Street Journal item [emphasis added] reminds you to wrestle with that question:
It's probably time to revise your will. In January, the federal estate-tax exemption jumps to $2 million per person, from $1.5 million this year. What's more, some states have different estate-tax exemptions. But many wills don't take into account possible changes in federal and state estate-tax rules.
Check with a lawyer to make sure the language in your estate plan still applies with new exemptions. If some plans aren't adjusted, you could, say, inadvertently leave little to your spouse or face an unexpected state tax hit.
Many people's wills also don't reflect their current inheritance wishes because of a major life change. And if a bank or trust company is the executor of your estate, you might have a new executor due to consolidation in the banking industry. Make sure you trust that executor's judgment.
The good news? If you're with a local institution, you have some will-appointment harvesting to do.
It's probably time to revise your will. In January, the federal estate-tax exemption jumps to $2 million per person, from $1.5 million this year. What's more, some states have different estate-tax exemptions. But many wills don't take into account possible changes in federal and state estate-tax rules.
Check with a lawyer to make sure the language in your estate plan still applies with new exemptions. If some plans aren't adjusted, you could, say, inadvertently leave little to your spouse or face an unexpected state tax hit.
Many people's wills also don't reflect their current inheritance wishes because of a major life change. And if a bank or trust company is the executor of your estate, you might have a new executor due to consolidation in the banking industry. Make sure you trust that executor's judgment.
The good news? If you're with a local institution, you have some will-appointment harvesting to do.
Paint the bullseye on the hedge funds
Hard on the heels of this New York Times article suggesting that pension funds have been investing heavily in hedge funds comes this new report from Investment News—Hedge fund boom worrying regulators (registration required). The net worth limitation, intended to narrow access to hedge funds to sophisticated investors, was set in 1982 at $1 million and has never been amended.
The net worth and income requirements may both be modified if the trend toward bring hedge funds to a wider audience continues, according to regulators. However, such restrictions likely won't apply to pension funds, whose managers presumably have all the necessary financial sophistication to choose investments wisely. Still, given the temptation for underfunded plans to load up on hedge funds in an attempt to reach solvency, coupled with demonstrated industry volatility (and scandal), one has to wonder about the exposure of the PBGC.
Are the wealthy asking their trust officers about hedge funds?
The net worth and income requirements may both be modified if the trend toward bring hedge funds to a wider audience continues, according to regulators. However, such restrictions likely won't apply to pension funds, whose managers presumably have all the necessary financial sophistication to choose investments wisely. Still, given the temptation for underfunded plans to load up on hedge funds in an attempt to reach solvency, coupled with demonstrated industry volatility (and scandal), one has to wonder about the exposure of the PBGC.
Are the wealthy asking their trust officers about hedge funds?
Subscribe to:
Posts (Atom)

 Posts


