Wednesday, February 06, 2013

Corporate Law and Trusts No Longer Mix

Debevoise & Plimpton, prominent New York law firm, has decided to abandon its trust and estates practice, The New York Times reports. Estate planning clients don't like paying the firm's going rate of over $1,000 per lawyer-hour. The firm's other partners don't like giving the trusts and estates partner the same million-dollar-plus annual bonus bestowed upon corporate deal makers.

(For a wicked but entertaining portrait of a big corporate law firm, see John Grisham's "The Associate.")

This sign of the times should not be taken as a putdown of trusts and estates work, says Sanford Schlesinger: “Families are going to pass more wealth in the next 10 years than in the history of humankind, and someone is going to have to shepherd that wealth transfer.”
•
The Times still refers to Debevoise as a "white shoe" law firm. How many of today's Times readers actually remember the days when Ivy Leaguers wore dirty white bucks?

Sunday, February 03, 2013

Woe to the Trusting Active Investor

From Ron Lieber's column in The Times, we learn that golfing in the investment jungle may have been costly indeed. Not only was the broker Philip Horn defrauding his golfing buddies, he seems to have traded ETFs and otherwise churned his clients' accounts. Lieber cites a study suggesting that actively traded accounts sacrifice three or four percent of return annually. If so, a Horn client with $10 million could have lost out on $300,000 or more per year.

Also in the Sunday Times, Paul Sullivan marks the 20th anniversary of exchange traded funds. The first exchange-traded index funds were a great idea. The proliferation that has followed – not so great. Also, ETFs make it awfully easy to jump in and out of markets and market segments. The temptation is costly but hard to resist.

Postscript. Walking around town this morning, a wealth manager's sign caught my eye. I snapped a photo, though I couldn't quite put a finger on why the sign struck me as odd.

As I wrote this post it came to me. Look at the tagline (to protect the innocent, I've obscured the firm's name).

"Trusted wealth advisors."

Philip Horn was a trusted adviser. For that matter, so was Bernie Madoff. What investors need are trustworthy advisers. Significant difference, don't you think?

Thursday, January 31, 2013

Penalty for Tax Evasion: Almost $22 Million!

Tax evasion is getting costly. Example from The Wall Street Journal: 
The U.S. government already has won about 50 criminal cases and collected at least $5.5 billion in connection with undeclared offshore accounts. On Jan. 8, Mary Estelle Curran, a 79-year-old widow best known for volunteer work, pleaded guilty to criminal charges of filing false tax returns and evading about $668,000 in federal tax on $40 million her husband left her in a secret Swiss bank account at UBS. She agreed to pay almost $22 million, which is believed to be the largest penalty in a criminal case on offshore accounts since the UBS agreement.
Ms. Curran is scheduled to be sentenced in West Palm Beach, Fla., federal court March 26. She faces up to six years in prison.

Tuesday, January 29, 2013

In 1963 Macho Investors Didn't Take Cruises

We've shown you cruise season ads from half a century ago. Here's one that takes a contrarian tack. Real men don't flee to the Caribbean. They stay home, brave the frigid wind and go ice boating.


Chase ran a lot of nest egg ads. This one may take the prize for most precariously perched egg.

Monday, January 28, 2013

Perils of the Art Market

Anybody who bids on "genuine Picasso prints" at a cruise ship auction, as described in Protect Your High-Net-Worth Buyers From Art Ripoffs, probably deserves what he or she gets. But art fraud isn't always obvious. Do high-net-worth art buyers need more protection?

The New York Times thinks so, citing fictitious starting bids at major art auctions and, worse, bids by third parties who have already agreed to buy a painting but who will receive a cut of the profits if they can coax an unwary collector to pay a higher price.

And why do New York art dealers almost never post the prices of works displayed in their galleries, even though they're legally required to do so?

Maybe the art market does need regulating.  Or does risk add zest to art as an "alternative asset?"
•
As a public service, here's a real Picasso print.


See Nicholas Forrest: How to Spot a Fake Picasso

Thursday, January 24, 2013

Quiet Trusts

Imagined dialogue from late last year:

Top Wealthholder: O.K. Let's put $10 million in trust for our kids and nail down our gift tax exemptions before they disappear. But….

Estate Planner: But what?

TW: I just realized. Once our kids learn about this trust, they'll never work a day in their lives!


EP: Who says they have to know? 

Quiet trusts, also known as silent trusts, gained both fans and foes in the Great 2012 Gifting Stampede. This WSJ column suggests wealthholders will continue to move assets into trusts for unsuspecting beneficiaries.

Is secrecy a good idea? Your answer may show your age:
According to some advisers, whether people favor quiet trusts or not often depends on their age. Older advisers, and older clients, are more likely to think keeping an inheritance secret "is a terrible idea," said Jonathan J. Rikoon, chair of the trust and estates group at law firm Debevoise & Plimpton LLP. Age has given them enough experience to see how secrecy actually plays out, Mr. Rikoon added.

Newer practitioners, especially those working with a new generation of entrepreneurs, may be likelier to see value in keeping things quiet.
This blogger sides with the seniors. (He knows his place.) As a comment to one of the WSJ columns points out, kids who grow up with maids and butlers already expect trust funds. There's nothing to hide.

And there's nothing new about secret inheritances. See Quiet Trusts and Great Expectations.

Saturday, January 19, 2013

“Go Someplace Warm. Leave Your Investments With Us”

Why stay in the snow belt? Take a cruise to someplace warm!

Good idea now, and a popular idea fifty years ago. In 1963 even ocean liners were offering cruises. They had to. Jet planes had drained their transatlantic business.


The couple in this City National ad seems to have skipped the cruise and simply hopped a plane to Colombia.

Why would a well-heeled investor wear a business suit on vacation? Because that's the way it was in 1963. (Times were about to change, drastically.)

Trusts For Gun Owners


January 19th is Gun Appreciation Day– an appropriate occasion to wonder whether gun trusts will increase along with gun ownership.

Gun sales have surged recently. Many buyers reportedly want to add to their collections before a feared government crackdown on sales of semi-automatic weaponry. Others are most likely speculators, looking to flip guns rather than houses.

Thus far, gun trusts have been used to facilitate and share ownership of special types of firearms – including machine guns and sawed-off shotguns – that have been taxed and regulated since the days of Al Capone. Will gun trusts proliferate in response to new restrictions?

Wednesday, January 16, 2013

Will Estate Planning Go Down Market?

For many attendees at the Heckerling Institute of Estate Planning, Deborah Jacobs reports, "it's the end of an era."

The era finished big, as top wealth holders rushed to transfer millions before assets over $1 million became subject to federal transfer taxes. They needn't have bothered. Five million or more continues to be exempt.

This year estate planners may keep busy holding the hands of clients who wonder what they were thinking: "Why did we give that much to our kids?" Next year, Jacobs suggests, tax audits will give planners plenty of work defending their intricate gifting mechanisms. After that . . . ?

Elder law is one option featured at Heckerling. Unfortunately, crass TV and radio commercials have given practitioners an unsavory image. But there's much more to elder law than syphoning off Mom's assets before moving her into a Medicaid-financed nursing home. This video from Bernie Krooks, one of the Heckerling presenters, shows why even something as basic as a durable power of attorney deserves careful thought.

Alas, it's unlikely that drafting revocable trusts and durable powers will pay as well as inventing clever ways to give away $5 million.

Friday, January 11, 2013

Estate-Planning Advice From Unprintable Web Site

In The New York Times Ron Leiber writes that he came across this web site last Tuesday. Does it prove the power of expletive marketing?

$5.25 Million

Bet Jim Gust wasn't the only one wondering what the inflation-adjusted value of the 2013 federal estate-tax exemption (sorry, the "basic exclusion amount") would be. The answer, Deborah Jacobs reports, is $5.25 million.

Wednesday, January 09, 2013

Clowning Around With Taxes

Who says our Congress is full of petty partisans and grouchy grinches? Two Georgia Congressmen have lightened the mood by sponsoring a bill to do away with the income tax, the estate tax and –yes – the Internal Revenue Service.

For funding, they propose that the federal government rely on a national sales tax – high in rate but gaping with loopholes – administered mainly by the states.

Should they have tried out H.R. 25 at an Atlanta comedy club before going national?
•
Caution: Go ahead and snicker at the idea that Uncle Sam should stop collecting taxes. But be aware that the idea of a national sales or "consumption" tax – to supplement, not replace, the income tax – has a number of serious advocates.

Monday, January 07, 2013

Golfing in the Investment Jungle

The broker was a really nice guy, a golfer who spent much of his time on the course, dispensing tips on hot stocks between holes. Once you signed up as a client, he handled your paperwork right there in the club parking lot. What more could a multimillionaire ask?

Using Philip Horn, rogue broker, as exemplar, Dealbook asserts that Financial Fraud Defies Policing. No Madoff, Horn rigged a system that allowed him to trade with his clients' money and skim off the profits.

Some comments appended to the Dealbook article express little sympathy for Horn's victims. You can see their point. One golfer invested $10 million with Horn but couldn't bother to look at the 50-page statements (implying at least ten or twenty double-sided pages of trades per month?!?) that he received from Wells Fargo. "If I had time to do that, I wouldn't need a broker."

Decamillionaires with that attitude should stay out of the investment jungle – or hire a fiduciary.

Friday, January 04, 2013

The new marriage penalty tax

I wasn't the only one who noticed that a pretty big marriage penalty tax has been added for those in the top 1% of earners.  Here's some details, and the math.

Evidently our Congress critters believe that having a spouse who works is the ultimate luxury.

Tuesday, January 01, 2013

Balanced?

You may recall that Obama called for a "balanced" approach of spending cuts and tax increases.  I remember when President Reagan accepted a deal for $2 of spending cuts for every $1 of tax increases in TEFRA.  The tax increases hit immediately, the promised spending cuts never materialized.

So perhaps we've become a bit more honest in our presentation. The newest deal includes $1 of alleged spending cuts for every $41 of tax increases, according to the CBO.  One wonders why they even bother.

This will be why many Republicans will vote against the deal in the House, but most of the Democrats will get on board. I think it likely to pass.

I also think it's a good time to buy some tax-free munis, and take a wait and see posture on stocks.  After-tax stock returns are about to be hammered, and the value of tax free income will soar.

After all this struggle, will Congress return to meaningful tax reform later this year? Given that the new rates and that AMT patch would be permanent, I seriously doubt it.

Here is the Senate bill.

I'd like to know the federal estate tax exemption for 2013, if anyone sees it.  From my reading of the Senate bill, the exemption is $5 million indexed for inflation since 2010, so it should be higher than the $5.12 million we had in 2012. 


Dangerous Inflation Ahead?

If the House passes the bill already approved by the Senate, the $5-million federal estate tax exemption will be indexed to inflation. Rep. Chris Van Hollen (Md.), the ranking Democrat on the House Budget Committee, expressed dismay. He suggests the cost of living could increase 50% by 2020.

If so, you'll need to pay $15 in 2020 for stuff you now purchase for $10.

Maybe it's finally time to get out of bonds.

Monday, December 31, 2012

Happy New Tax Year!

If this evening's agreement gains approval by the Senate and House, estates of $5 million or less will continue to avoid federal estate tax, though larger estates will face a 40% tax rate.

More good news: the annually-threatened imposition of the Alternative Minimum Tax on ordinary taxpayers will be fixed "permanently."

Not so good news for high-income taxpayers: a higher tax rate for couples with incomes over $450,000, a phase-out of deductions for those with incomes over $300,000.

Meanwhile, pending Congressional action, off the fiscal cliff we fall. The New York Times came up with this icon for the occasion.

Estate Tax Debate Goes Down to the Wire

Representative Lynn Jenkins (R), December 20:

Growing up on a Kansas dairy farm, I know the estate tax is a threat to family farms. This tax makes bailing hay and shoveling manure sound like a get-rich-quick scheme, when most family farms make an average of $45,000 a year. Raising the estate tax to 55 percent and dropping the exemption to $1 million might be feasible for a hedge fund manager, but it will jeopardize the future of farmers and their families….

Senator Richard Durbin (D), December 30:

I am troubled by the notion we are somehow going to give [an estate tax] break to some 6,000 very fortunate Americans and incur a new [sic] expense for our Federal Government of some $130 billion or $140 billion in the process. What are we thinking? *** I hope we aren't forced into any agreement that includes it, although I stand here knowing full well if there is an ultimate compromise, there will be parts of it I find disgusting and reprehensible which I may have to swallow….

Care to pick a winner?

Friday, December 28, 2012

We're going over the cliff!

Earlier I mentioned that the only possible way to avoid the fiscal cliff over a very short time frame was for the House to pass S. 3412, which already passed the Senate last July. It provides a one-year extension of the status quo, plus an AMT adjustment for 2012.

Today I learned from Tax Notes that such a path is technically impossible, because Majority Leader Reid never sent the paperwork to the House!  Plus, there's that irritating constitutional requirement that tax legislation originate in the House.  Usually some shell legislation is used to get around that, but that apparently wasn't done for S. 3412.

So, the only remaining path is identical legislation that has been brought to the House Ways and Means Committee.  Evidently, if the House will pass that, the Senate will be available to re-pass it.

It would be another kick of the can down the road.  My feeling is that both sides want to go over the cliff, if only they can be confident that the other side gets the blame.

Is it "Throw Grandma From the Train" time again?

There was much speculation in 2010 that, in the absence of estate tax reform, there would be an uptick in deaths among the wealthy elderly simply to avoid estate taxes. 

Absurd? CNBC has collected some relevant facts on elasticity in dates of birth and death.

By keeping hope for estate tax reform alive until the end of the year, I suspect the problem has been avoided. Had Congress reached an agreement in November to, for example, reduce the federal estate tax exemption dramatically on January 1, perhaps the decisions to withdraw life support might have been accelerated for some families. 

We've known the cliff was coming for two years, but I never believed we'd actually go over it.

Thursday, December 27, 2012

State death taxes are about to be resurrected

Fewer than half the states impose death taxes this year.  The decline of state death taxes began with the elimination of the federal estate tax credit for payment of state death taxes, phasing out after 2001.

Please note that I am not making a political statement when I use the politically charged term "state death taxes."  That was what the tax code called the credit, it didn't come from an anti-tax focus group.

When the credit was converted to a deduction, the impact on taxable estates was nominal. But the impact on states was huge, because they could no longer impose the "mop-up" version of a state estate tax, linking their death tax measurement to the federal credit.  Some states thus lost the ability to impose a death tax, based upon state constitutions, and others gave it up voluntarily.  In the larger scheme, this was a revenue grab by the feds from the states, and it worked.

When the Bush tax cuts expire, as they surely will, the deduction for state death taxes will go back to being a credit.  Most states may be expected to restore their death taxes.   Conveniently, the federal exemption of $1 million matches the exemption of many of the states that had decoupled from the federal system to preserve their own death taxes.

Apparently, California is already counting on this new revenue source.  Makes me suspicious.  I wonder if anyone was ever really serious about avoiding the fiscal cliff? Maybe both sides really wanted to go over it, which is why all the jockeying is about who gets the blame?

Friday, December 21, 2012

The Hardest Time to Invest

Disaster struck at 6:11 p.m. EST today – the world did not end. Skittish investors were left to face a looming fiscal cliff, a dysfunctional federal government. Surely this must be the hardest time to invest.

Yes, it is. It always is.

In this classic U.S. Trust ad from the December 29, 1962 issue of The New Yorker, the founder of the Merrill Anderson Company stated an eternal truth:
Investment decisions are always difficult, but always necessary.

Tuesday, December 18, 2012

Whither the Estate Tax?

The President and the Republicans may be nearing a deal to avert a plunge off the fiscal cliff. Any guesses about what next year's federal estate tax will look like? The President has proposed a $3.5 million exemption and a 45 percent tax rate.

Republicans, if they can't have no death tax at all, want a higher exemption and a lower tax rate. So do some Democrats, especially from farm states. Although housing prices slumped and in some places crashed during the Great Recession, agricultural land prices have kept rising. "Land selling for $1,000 an acre five years ago may now be worth five or 10 times that amount," notes The Modesto Bee.

Most recent support for a much harsher estate tax comes from a group of rich business notables. They see our nation's fiscal instability as a greater threat to wealth than taxation.

Actually, billionaires don't have to worry much about estate tax, unless they own one of the very largest family businesses. Usually a $4-billion family can get along just fine on $2 billion.

For background, see this history of the federal estate tax. One table, reproduced below, shows the remarkable ups and downs in both rates and exemption level from 1915 to 2007. (In 2010, of course, rates and exemptions reached their irreducible minimum: zero.)

Click for larger image.

Monday, December 17, 2012

Santa Money

Once upon a time, Americans used more than 8,000 kinds of money. Any bank could issue notes. One $5 example from the 1880s just sold at auction for over $100,000. 

This Huff Post item links to a wild and crazy slide show of old currency, including the Confederate variety. Check out this Howard Bank note with a vignette of Santa Claus. 

Friday, December 14, 2012

The Muni Bond Loophole

You know that a tax preference is in trouble when it begins to be labeled a "loophole" in the popular press.  The tax freedom for municipal bond interest is starting to get that treatment.  See this, for example.

Personally, I think that eliminating the tax freedom for all future muni bonds is a great idea.  Of course, the value of existing tax-free bonds will then zoom, so there would be some windfall profits. That's the transition price to pay.

Meet the IMWIs

The Telegraph calls attention to a survey of "Internationally Mobile Wealthy Individuals." Real estate is a favored investment, especially among those based in the Asia-Pacific region. U.S. and Canadian millionaires who spend more than half their time outside their home country are more likely to favor stocks, less likely to own three or more homes.

More data from the survey here.

Thursday, December 13, 2012

Quality is recognized

Professor Gerry Beyer's estate planning blog is having stunning success.  Visitors and page views are up over 20% in the last quarter, and his is the 20th most popular law professor blog in the country.  (Only those who have site meters are included in the survey.) 

Professor Beyer's blog is well worth your time, which is why we keep a permanent link to it in our template. He's also an occasional contributor to our Estate Planning Studies. 

Wednesday, December 12, 2012

S. 3412

Following up on this post, the bill the Senate approved is S. 3412.  It passed the Senate 51-48.  Interesting that the Republicans neglected to filibuster it.  To correct my earlier post, it won't need to be taken up by the Senate if the House doesn't change it, it will go straight to the President.

That's the outcome I now expect.

To answer the lingering question in that earlier post, S. 3412 does include the AMT patch.  That bolsters the odds that this is the legislation that will be enacted.  I've read that a retroactive AMT fix, after the new year begins, is theoretically possible but inevitably would delay refunds even more.  It's a bad, bad idea.

More info on S. 3412 is found here.

I've read the entire bill, which is quite short.  But it's written in legislative bafflegab, as amendments to prior legislation, so the meaning is hard to ferret out.  Specifically, I'm unclear on what happens to the estate tax, which is not directly mentioned.

In any event, passage of this bill would mean we get to do this all over again next year, as it is for 2013 only. Theoretically, the idea seems to be that tax reform will really, really, finally, be attended to next year.

Want to restore economic growth? Go back to the bipartisan 1986 tax reform act, and you'll get your economic growth back.

Thursday, December 06, 2012

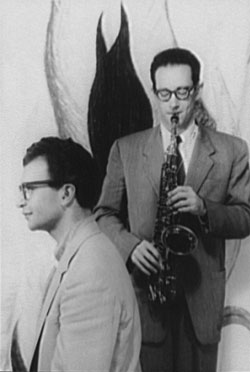
Brubeck and Desmond: the "Take Five" Bequest

Dave Brubeck and Paul Desmond,
October 8, 1954
Dave Brubeck's most memorable hit was"Take Five." Taylor Ho Bynum reminds us that the tune became a significant charitable bequest.
...like the partnership between Duke Ellington and Billy Strayhorn, [the collaboration between Dave Brubeck and Paul Desmond] was a relationship of matched brilliance. And like Ellington’s “Take the A Train,” actually penned by Strayhorn, Brubeck’s signature tune “Take Five” was composed by Desmond.
In the month post-Sandy, we should also remember that when Desmond died, in 1977, he bequeathed the royalties to “Take Five” to the American Red Cross, bringing the organization close to six million dollars. With that composition sure to receive a flurry of performances after Brubeck’s death, it will likely bring in tens of thousands of dollars more to disaster relief at a time when it is sorely needed.

Wednesday, December 05, 2012

"Have I Got a Hedge Fund For You!"


At Dealbook Jesse Eisinger takes a few playful pokes at the proposed lifting of restrictions on advertising hedge funds.
The rules haven’t been completed, but we can look forward to an ad featuring a wizened couple in matching tubs overlooking a sunset, holding hands and talking about how they just put money with the next George Soros.
Once deluxe investments for university endowments and wealthy individuals, hedge funds have found their way into the portfolios of less sophisticated institutional investors. Now they're poised to target the millionaire next door.

Will the effort further dim their cachet in the high-net-worth market? Eisinger thinks so: 

"If Groucho Marx were alive today, he'd say that he would never want to invest in a hedge fund that would have him as a limited partner."

Tuesday, December 04, 2012

End game

I don't think that the tax negotiations will end well this year.

Two years ago, the historic compromise was reached by December 6, and we started to blog about it here.    The legislative process was completed in just 11 days, by December 17, showing just how fast Congress can act when Christmas is coming.

No signs of compromise at all this year.  I just don't see how anything can be drafted by year end.

However, apparently the Senate produced legislation last summer to implement an extension of the Bush tax cuts to the bottom 98%.  It didn't have anything on the payroll tax holiday, the debt ceiling, or unemployment benefits.

ABC News reports on a "doomsday plan" by the House Republicans to bring that Senate legislation to the floor.  It does what Obama and the Democrats claim that they want.  Bringing it to the floor "releases the hostage" of the middle class tax cuts.  All Republicans would vote "present," so the bill would pass.  In the minds of Republicans, failing to stop a tax increase is different from voting for one.  I don't see the practical distinction myself.  But at least they could no longer be blamed for allowing the tax increases on the middle class, which is the corner that the Democrats backed them into.

Would the Senate bring it up? Would the President sign it?  It looks to me as if a surprising number of Democrats prefer to go over the cliff instead.

I haven't found the bill yet.  My question, did it include the inflation adjustment for the 2012 AMT?

Tax Notes reports that the IRS has already programmed their computers for another inflation patch to the AMT, assuming that Congress would never let that expire.  Some tax failures can be retroactively fixed, like the lapsed estate tax, but not this.  Per Tax Notes, failure to patch the AMT now will do much more than impose the tax on many more taxpayers, it will also delay tax refunds for everyone else by six weeks or so.  That delayed cash flow alone could have negative economic fallout.

If that Senate bill includes the 2012 AMT patch, I believe that the Senate would act and President Obama would sign it.  But that has to be concluded by December 17, when he leaves for Hawaii for the holidays.  I suppose that they could have a signing ceremony out there.

Final note.  This has been a titanic struggle just to leave the tax code unchanged.  Tax cuts have contributed to an economic bounce in the past.  Leaving the tax code unchanged has not.  Although the media talks about middle class tax cuts, no one will see lower taxes next year under any scenario.  Dodging a scheduled tax increase just doesn't excite the animal spirits the way ERTA did back in 1981.

Monday, December 03, 2012

Estate Planning Boom Ahead?

The President's proposal to cut the amount exempted from federal estate tax from about $5 million to $3.5 million could double the number of estates exposed to tax. Result, a surge in the number of families needing tax-effecient estate plans.

A few Democrats, including Senate Finance Committee Chairman Max Baucus, favor keeping the higher exemption. Which way do you think Congress will lean?

Sunday, December 02, 2012

Jeremy Siegel, Stock Market Pessimist

Happened on Jim Gust's July, 2010 post. He noted that Jeremy Siegel believed stocks were undervalued by 25-30%. Jim seemed dubious, and rightly so. The S&P 500 is not up 25-30% since the start of July, 2010.

 As of November 30, it's up 37%.

Getting a Man's Nest Egg With a Gun

Chase Manhattan's legendary nest-egg ads of the 1950's and 1960's usually featured manly pursuits – sailing, fishing…and, of course, shooting. See examples picturing men with guns here, here and here.

This ad from December, 1962 also shows a man with a gun – except that a Purdey shotgun or rifle is a gun only in the sense that a $60,000 Swiss chronometer is a wristwatch. Purdey provides sporting weaponry to The Queen, The Duke of Edinburgh and The Prince of Wales. One of their shotguns could set you back $100,000 or more.

James Purdey and Sons is now owned by Richemont, a Swiss luxury goods holding company. Richemont also owns several watchmakers.